Update
New Zealand agribusiness monthly October 2026: Longer days and new season dynamics



Here are the main highlights for some of New Zealand’s key commodities and economic influences this month. The full report provides an overview of the developments to watch in the upcoming weeks.
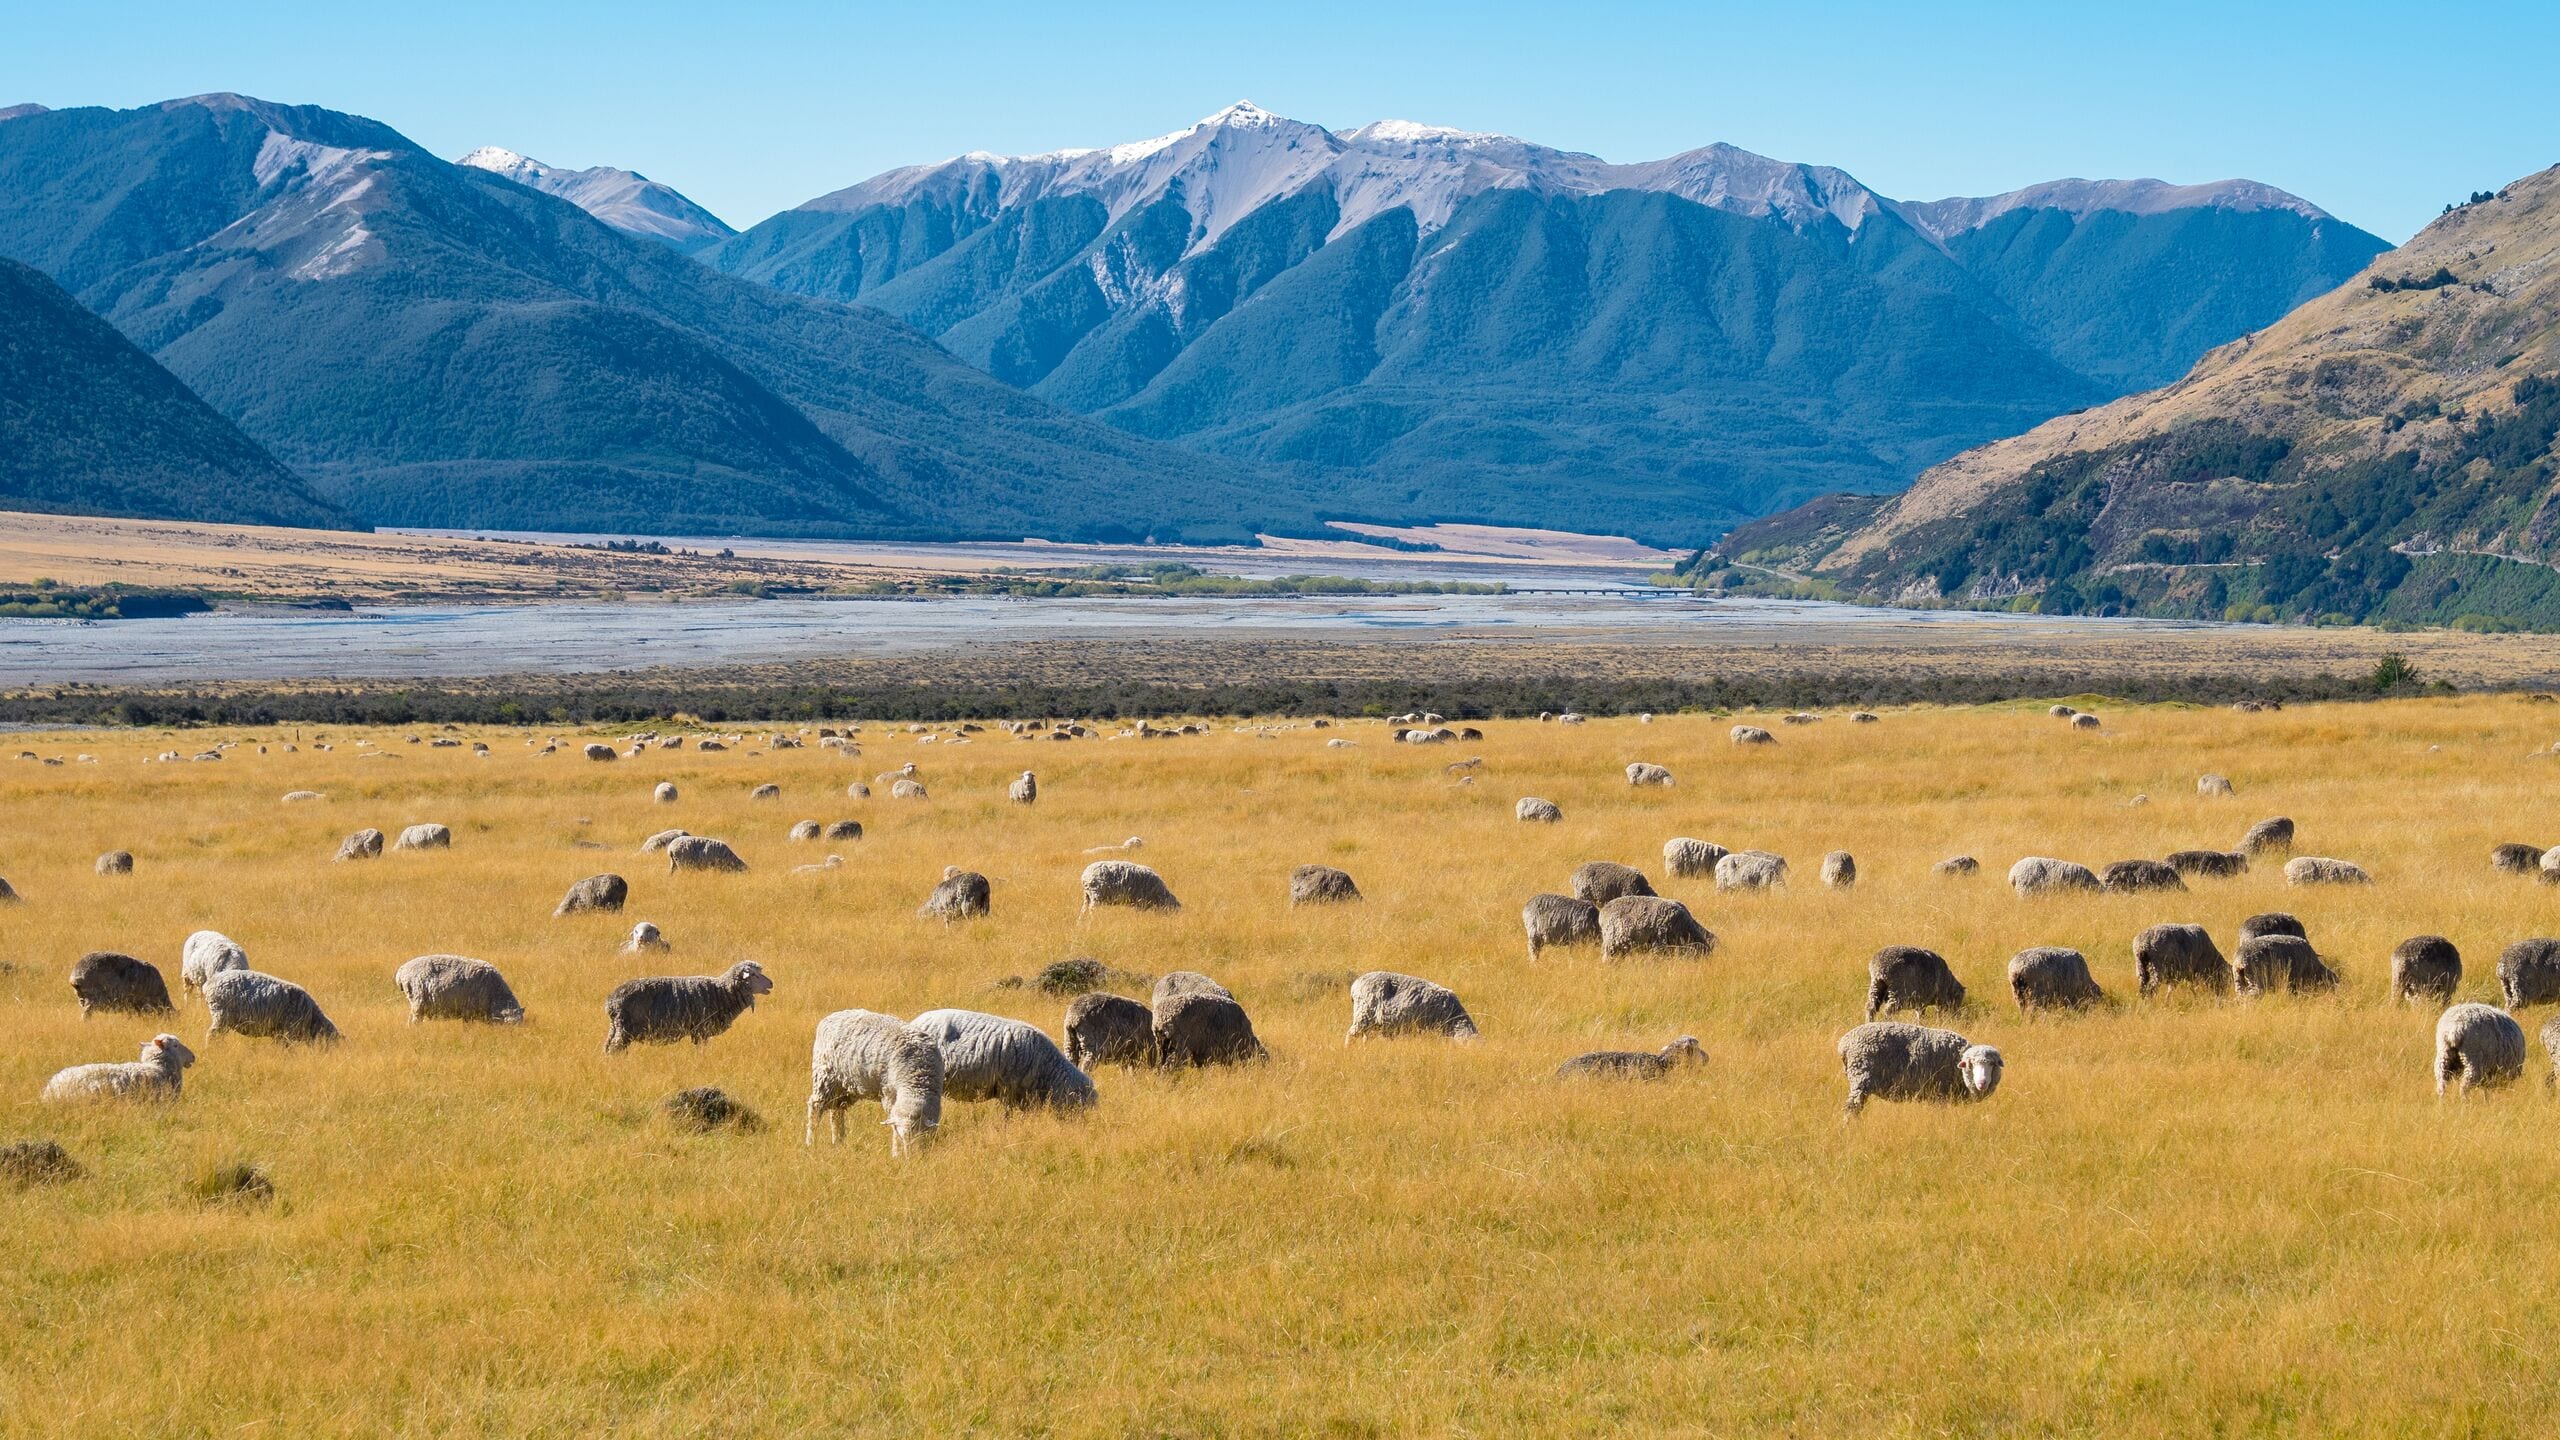
Dairy: Dairy commodity prices found support in September, although butterfat prices remained weak, and gains in protein prices were led by skim milk powder. Global fundamentals are transitioning towards a better balance as supply growth moderates.
Beef: Beef farmgate prices remain strong. However, rising seasonal supply and greater competition from Australian and Brazilian beef could slightly soften farmgate returns across bull and M-cow cohorts through to the end of the year.
Sheepmeat: Lamb farmgate prices remain firm, supported by tighter domestic and Australian supplies and diverse export markets. Southland’s challenging weather adds some regional nuance, while spring’s new-season lamb supply will test price sustainability.
Farm inputs: Fertiliser markets remained highly volatile through September, with elevated energy costs, Middle East shipping disruptions, and European production curtailments supporting nitrogen prices. Phosphate markets stayed tight despite softer demand.
Interest rate and FX: Market expectations for the path of the OCR lifted in September as oil prices rose. RaboResearch does not project a rate rise at the October RBNZ meeting but expects further tightening in December and February.
Oil and freight: Oil prices rose in September after drone strikes shut down Saudi Arabia’s East-West Pipeline. The prospect of a diesel export ban in the US is creating the risk of further upward pressure on prices in an already pressured market.